RESPONSIBILITY, IN WRITING.
Advisors advise. Consultants recommend. A fiduciary is legally accountable for the decision and can be held to it afterwards. When Apex serves as your independent ESOP trustee or as your 3(16) plan administrator, we take the role by name, under our own entity, and we sign.
We hold no ownership stake in your company and sell no investment products. Independence is not a line in a brochure here; it is the only reason the appointment means anything.
- Independent ESOP trustee
- ERISA 3(16) plan administrator
- Named in the plan document
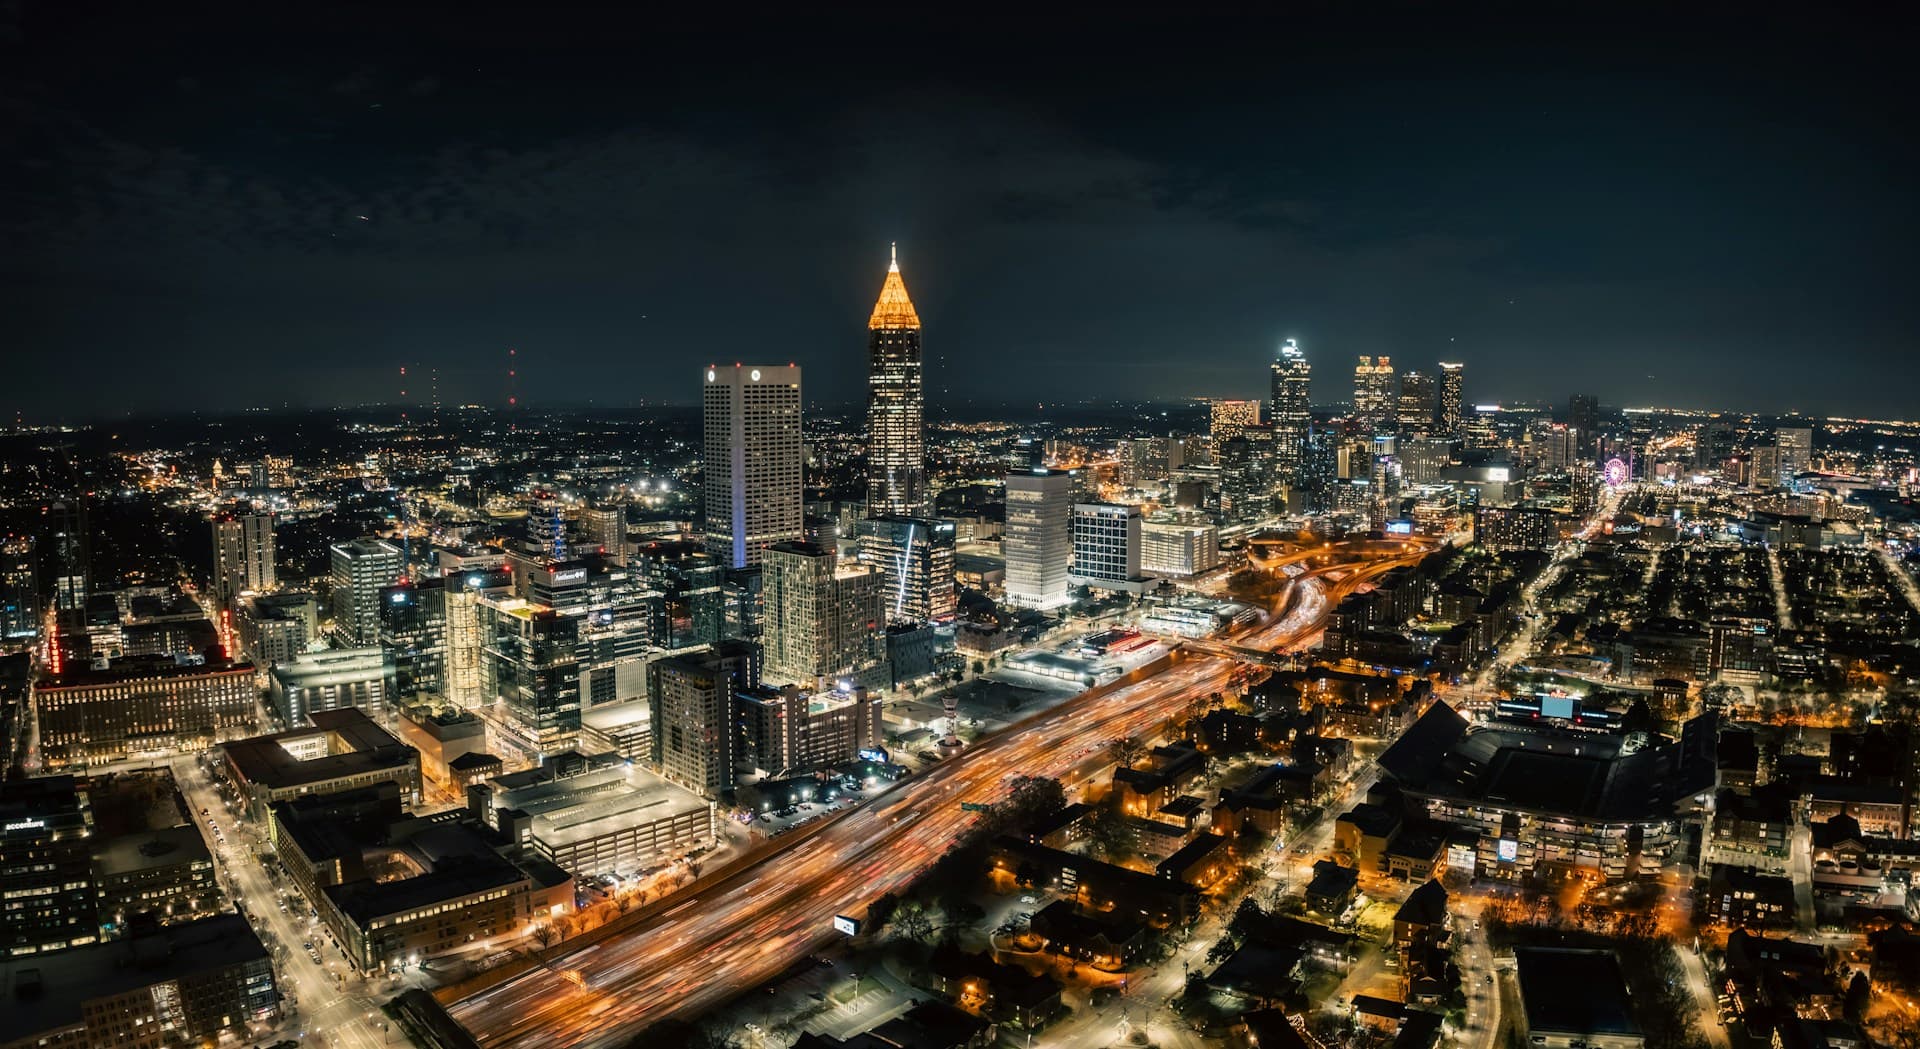
- Atlanta · since 2003
TWO APPOINTMENTS. ONE DUTY.
What we can be named asThere are two key roles where a retirement plan may require an independent fiduciary: the Trustee that holds employer stock in an ESOP and the Plan Administrator responsible for overseeing the plan under ERISA.
Apex Fiduciary Services can serve in either role, not simply as an adviser, but as the named fiduciary in the plan documents. That means accepting the responsibility, carrying the ERISA fiduciary duty, and being accountable for the decisions that come with it.
Named in the plan document. Bound by ERISA. Answerable, under our own entity, for every decision inside our scope. Fiduciary is a legal status with consequences attached, not a courtesy title a service provider gives itself in a proposal.
INDEPENDENT ESOP TRUSTEESOMEBODY HAS TO SIT ON THE PARTICIPANTS’ SIDE.
An ESOP is a retirement plan that owns the company its participants work for. That makes the trustee’s job unusually concrete. The trust holds the stock. Somebody independent has to decide what the plan pays for it, what terms the plan will accept, and whether the plan belongs in the transaction at all.
Independent ESOP trustee, in fullThe six-chapter case study series
AT THE TRANSACTION
We review the valuation, challenge the assumptions behind it, and negotiate price and terms on behalf of the ESOP, always with the interests of plan participants at the center.
We document the reasoning behind each decision and ask the questions that need to be asked. And if a transaction isn’t right for the plan, we say so.
Independence means being prepared to say yes when the terms are right, and no when they aren’t.
YEAR AFTER YEAR
The Trustee’s role doesn’t end at closing. We hold the shares, oversee the annual valuation, manage required voting, monitor plan operations, and document the decisions made along the way.
Structure
How the transaction and the trust are actually put together, and what each piece obliges the plan to do afterwards.
Design
How the plan itself is built: eligibility, allocation, vesting, distribution policy, and what it will cost the company to run for the next decade.
Negotiation
Fiduciary judgment applied to price and terms, negotiated fairly on behalf of the participants rather than the people selling.
Operations
Valuations, allocations, distributions and the repurchase obligation. The unglamorous years after the deal closes, where most failures start.
Structure, design, fiduciary judgment and operations, the same four things an ESOP needs from the day it is drawn up.
3(16) PLAN ADMINISTRATORTHE ROLE, TAKEN BY NAME.
Every retirement plan names a Plan Administrator, and most often, that’s the employer. That means someone inside the company is responsible for critical notices, filings, and deadlines, often without the training or resources the role demands.
Under ERISA section 3(16), that role can be given to someone else by name. Apex takes it. We issue the participant notices on schedule, prepare and make the government filings, and put our own signature on the Form 5500.
The Form 5500 gets our signature, not just our prep work.
The usual arrangement
- Named plan administrator
- The employer, typically represented by the business owner, the CFO, or a designated HR professional.
- Participant notices
- Drafted for you to distribute, against deadlines you have to track yourself.
- Form 5500
- Prepared for your signature.
- A missed deadline
- Your problem.
With Apex named as 3(16)
- Named plan administrator
- Apex Fiduciary Services, LLC, by name, in the plan document.
- Participant notices
- Distributed by us, on schedule, and documented so the distribution can be proved later.
- Form 5500
- Signed by us.
- A missed deadline
- Ours.
Naming a 3(16) does not turn the employer into a non-fiduciary. You still choose the appointee, and you still have to monitor the appointee you chose. What a 3(16) does is move a defined set of duties, in writing, to a firm that does them for a living. Anyone who tells you it does more than that is selling something. We set out the three misconceptions about liability relief below.
WHAT ERISA ACTUALLY REQUIRES.
Fiduciary status is not a compliment. It is a set of obligations with teeth, and there are four of them. They are short. They are not negotiable. And they apply to whoever is holding the role, which, until someone is named, is usually you.
- ERISA duty
LOYALTY
Act solely in the interest of the participants and their beneficiaries, for the exclusive purpose of providing their benefits and paying the plan’s reasonable expenses. Not the company’s interest. Not the board’s. Not ours. Where those interests point in different directions, the participants win. That is the whole content of the word loyalty here.
- ERISA duty
PRUDENCE
Carry out the duties with the care, skill and diligence of somebody genuinely familiar with these matters. Prudence is judged on process rather than outcome: what was examined, who was asked, what alternatives were weighed, and what was written down at the time. A good outcome reached carelessly is not a defense, and a poor outcome reached carefully is not a breach.
- ERISA duty
DIVERSIFICATION
Diversify the plan’s investments so as to minimize the risk of large losses, unless under the circumstances it is clearly prudent not to.
The ESOP exceptionAn ESOP exists in order to hold employer stock, so ERISA relieves it of the duty to diversify. The relief is narrow. It lifts diversification and nothing else. Loyalty, prudence and the plan document all still apply in full. In an undiversified plan they matter more, not less, because the concentration nobody is allowed to fix has to be justified by everything around it.
- ERISA duty
THE PLAN DOCUMENTS
Follow the plan documents, to the extent that they are consistent with ERISA. Which sounds procedural until you notice what it assumes: that somebody has read them, understood what they promise, and keeps reading them as the plan is amended and the law moves underneath it. Most operational failures are not exotic. They are a plan being run the way people remember it rather than the way it is written.
SOLE INTEREST
Every decision is tested against one question: is this in the best interest of the participants and their beneficiaries?
EXCLUSIVE BENEFIT
Plan assets exist to provide benefits and to pay the plan’s reasonable expenses. They exist for nothing else.
CARE AND SKILL
The standard is not good intentions. It is the appropriate care and skill of somebody who does this work properly.
HOW A TRUSTEE OPERATES.
The job between the headlinesPAY ATTENTION
A fiduciary who appears once a year is not paying attention. We follow the plan between meetings: contributions arriving on time, distributions going out correctly, eligibility being applied the way the document says, valuation assumptions still holding up against the business as it is now.
MEET REGULARLY
Scheduled trustee meetings with an agenda, minutes, and a record of what was decided and why it was decided that way. If it was not documented, it is very difficult to argue afterwards that it was prudent, and afterwards is when anyone asks.
REVIEW EVERYTHING
Not only the investments. Eligibility, allocations, vesting, loans, distributions, notices, filings and fees, all plan operations, because operations are where real failures start, quietly, and where they usually surface years later during an audit.
A TRUSTEE’S FIRST RESPONSIBILITY IS TO THE PARTICIPANTS.
That is not a tension we manage around; it is the appointment itself. It is also the reason an independent trustee is worth having. Somebody inside the company can be right about every technical question and still be structurally unable to give the unwelcome answer.
THREE MISCONCEPTIONS ABOUT LIABILITY RELIEF.
Straight answers, not sales copy“Appointing a fiduciary transfers all of my liability.”
It does not. Choosing an appointee is itself a fiduciary act. You remain responsible for having selected prudently and for monitoring what the appointee actually does. What moves is responsibility for the delegated function, not your judgment in delegating it, and not your obligation to keep looking.
“With a 3(16) in place, the employer is no longer a fiduciary.”
The employer keeps everything it did not hand over: the appointment, the monitoring, plan-level decisions such as amending or terminating the plan, and getting participant contributions into the trust on time. A named administrator narrows the exposure and gives it a professional owner. It does not end it.
“Independence is a formality: any third party will do.”
A firm that is paid on the transaction, that manages the money, or that owes its seat to the person across the table is not independent in the way that matters. Independence is the ability to say no and have the no stand. A fiduciary who cannot say no is not relieving anybody of anything. They are simply another signature on the same decision.
We believe in clarity from the start. We’ll explain the scope and limits of the fiduciary role before the appointment, not during an audit. And if the arrangement isn’t right for your plan, we’ll tell you that, too.
CONSIDER THEINDEPENDENCE.
An independent fiduciary has no ownership stake, investment products to sell, commissions to earn, or internal politics to navigate. What remains is what matters: independent judgment, focused expertise, and a clear responsibility to the plan and its participants.
- No ownership stake
- No investment products
- No commissions
- No seat on the board
PARTICIPANTS
Their benefit is the only interest an independent fiduciary is permitted to serve, and the only one it is measured against.
THE PLAN SPONSOR
The company gets a documented, defensible process instead of a decision nobody in the building wants to own.
OTHER FIDUCIARIES
Owners, officers and committee members stop carrying decisions alone that they were never equipped to make alone.
WHO YOU ACTUALLY GET.
No call center, no rotating account team. These are the names on your plan, and the ones who answer when you call about it.
Michael Miller, CEBS
CEO, President and Trustee
With over 35 years of retirement planning expertise, Michael specializes in navigating the complex world of ESOPs and corporate pension plans. He blends high-level legal strategy with practical, day-to-day compliance monitoring to protect both client companies and their employees. A graduate of Emory University with a Wharton CEBS designation, Michael is a trusted industry partner known for making complex regulatory topics simple, efficient, and actionable.
CEBS · Emory University · Wharton
Diana Clark, MS, PHR
VP of Marketing and Employee Ownership
An accomplished leader with more than 20 years of experience leading brand strategy and employee ownership. She combines expertise in marketing and human resources to advance clients' employee ownership initiatives, strengthening workplace culture and organizational impact.
Apex Pension Strategies, Inc.Apex Fiduciary Services, LLC
Kim Carmichael
COO
An accomplished benefits leader with more than 20 years of experience driving excellence in plan design, administration, and compliance. Proven track record managing trust accounting and regulatory frameworks across high-stakes industries, including healthcare, logistics, and finance. Committed to delivering robust, compliant, and cost-effective plan solutions.
Apex Pension Strategies, Inc.
Leander MacVane, APA
Director of Sales and Business Development
With more than 35 years in the retirement plan industry, Leander brings deep expertise from both the operational and consulting sides of the business. Having spent much of her career managing retirement plan processes within TPA practices, she understands what it takes to turn thoughtful plan design into a smooth, successful experience for employers. Leander partners with financial advisors, CPAs, wholesalers, and plan sponsors to evaluate plan options, identify the right solutions, and bring the right people together. Her relationship-driven approach focuses on making the process clear, collaborative, and as easy as possible for the plan sponsor.
Apex Pension Strategies, Inc.
Trey Stephens, MS, MBA, ERPA, QPA, QKA
Retirement Plan Administration
An accomplished retirement plan specialist with over 25 years of administration experience and comprehensive expertise in every plan type offered by APEX.
Apex Pension Strategies, Inc.
Jeffrey Koppes, MBA
Jeff brings firsthand company-side ESOP transaction experience backed by decades of financial leadership to our clients. He draws on his broad financial and operational expertise to help clients navigate valuation, transaction structure, risk, and long-term ESOP sustainability.
Apex Fiduciary Services, LLC
Michael Shields, MBA, CPA
An experienced CPA and business leader, Michael brings a strong background in audit, tax and employee ownership. With comprehensive ESOP experience, he works closely with clients to support the operational and financial aspects of their ESOP and help ensure plans operate effectively throughout the life cycle of the Plan.
Apex Fiduciary Services, LLC
THE SAME TEAM ALSO RUNS THE PLAN.
Apex Pension Strategies, Inc. is the third-party administration practice handling plan design, administration, compliance testing, and consulting, all with one consistent team. The people who design your plan are the people who run it.
NAME A FIDUCIARY.
Tell us what the plan needs. An independent trustee for an ESOP transaction you have coming. A 3(16) so the notices and the Form 5500 stop being somebody’s side job. Or a straight answer on whether you need either one. You will speak to the person who would do the work.